What are some of the exciting developments you are seeing in Canada?
Arthur Kolodziejczyk: The Canadian market is going through an exciting period of change, particularly in securities finance and repo. Improvements in market infrastructure, a greater focus on collateral optimisation, and advances in technology are creating opportunities to make the market more efficient and accessible.
One of the most important developments is the modernisation of the Canadian repo market. Initiatives such as the Canadian Collateral Management Service (CCMS) are set to improve operational efficiency, standardise processes, provide greater access, and support greater liquidity in the domestic market. The Bank of Canada has confirmed it will start using CCMS for its own repo operations in the first quarter of 2027, signaling central bank endorsement that should encourage broader market adoption.
Separately, the introduction of the fail fee framework for Government of Canada debt instruments, which commenced in September 2026, marks a structural shift in Canadian market discipline. The trial runs for a minimum of 18 months, during which fails are calculated but not charged, giving participants time to prepare before payment exchange is activated. Combined with CCMS, these changes should help strengthen market discipline and support continued market development. We are also seeing broader participation across the market, creating opportunities to expand repo beyond traditional institutional channels.
Another key theme is the growing importance of balance sheet and collateral optimisation. With T+1 settlement in North America now in place and Basel III liquidity requirements continuing to influence how institutions manage their balance sheets, firms are increasingly focused on funding efficiency and maximising the value of their assets. This is driving demand for term lending, particularly in the 35-to-185-day space, as well as greater flexibility in collateral eligibility.
For beneficial owners, the growing acceptance of non-cash collateral, including equities and corporate debt, means greater optionality in how they deploy idle assets: non-cash collateral unlocks lending capacity without tying up cash, which is increasingly valuable as balance sheet costs rise.
On the technology front, tokenisation and distributed ledger technology (DLT) could help streamline collateral movements, improve intraday liquidity management, and create greater efficiencies across markets. In March 2026, RBC Capital Markets and RBC Investor Services, alongside the Bank of Canada, TD Bank Group, and Export Development Canada, successfully completed Project Samara: Canada’s first tokenised bond issuance on a distributed ledger platform operated by RBC.
The regulatory conversation is also evolving: the European Securities and Markets Authority (ESMA) recently launched a consultation on tokenised collateral for EU central counterparties, signaling that supervisors are beginning to grapple with the same questions market participants are already working through. While adoption is still evolving, these developments could meaningfully change how market participants manage collateral.
The most exciting opportunity is seeing how these developments come together for our clients. For beneficial owners, the combination of better infrastructure, more flexible collateral, and continued technological innovation means a more efficient and competitive Canadian securities finance market in which to deploy their assets.
RBC Investor Services has team members in multiple jurisdictions to optimise coverage, cross-border flows, and local demand. How do you balance centralised decision-making with local market expertise?
Chris Barrand: Balancing centralised decision-making with local market expertise in a global, follow-the-sun agency lending programme requires a ‘federated’ governance framework. If the model is too centralised, regional desks can miss out on local market nuances and alpha generation. If it becomes too decentralised, the global book can become too fragmented, creating regulatory, credit, and operational risks. It is important to achieve equilibrium through a highly structured matrix of technology, risk parameters, and regional autonomy.
To protect the firm from systemic risk, centralised decision-makers maintain strict, non-negotiable control over the operational and technical foundation. Global risk and credit parameters are established centrally, while a unified global inventory and trading platform ensures all regional desks lend on a single, shared ledger. This prevents duplicate bookings, ensures real-time global position visibility, and allows for automated cross-border optimisation and exposure management. It also standardises handoff processes between the regions.
While the framework is centralised, trade execution is hyper-local. Our traders possess the relationships and market insights required to maximise our lending revenues. When it comes to pricing specials and capturing intrinsic value, local desks are granted pricing autonomy to negotiate the highest possible lending fees based on local supply and demand dynamics. Demand for specific securities across local desks can vary, as both market drivers and regulations differ region to region. This can extend to market nuances such as withholding tax treatments, stamp duties, and regional short selling restrictions, coupled with added complexity when issuing market recalls. Our traders also develop and maintain borrower relationships locally and are best equipped to deal with these local market nuances.
Which new markets do you believe would be ready for foreign-to-foreign securities borrowing and lending across the various regions?
Juhi Chikhlia: We continue to see Indonesia and the Philippines as two of the more promising emerging lending markets in APAC, as both markets progress reforms aimed at developing their domestic securities borrowing and lending (SBL) frameworks.
Indonesia has taken a meaningful step forward with the phased reinstatement of short selling transactions from October 2026, while maintaining a focus on infrastructure readiness, risk mitigation, and supervisory effectiveness. In the Philippines, the Philippine Stock Exchange has continued to engage market participants on proposed enhancements to its SBL rules, including collateral management and reporting requirements.
Vietnam is another market worth watching closely in the long term. Its reclassification to FTSE Russell Secondary Emerging Market status in September 2026 follows broader reforms designed to improve access for international investors. India and China also remain significant longer-term opportunities given the size of their capital markets, albeit with more distinct domestic market structures.
Beyond APAC, Brazil is shaping up to be the next significant frontier for foreign-to-foreign lending. The International Securities Lending Association (ISLA) Americas has been collaborating with B3 for over two years on a proposed bilateral lending model that would allow collateral to be exchanged offshore while securities settle locally — a structure that would unlock international capital currently shut out by Brazil’s central-counterparty-only framework.
Ultimately, scalable foreign-to-foreign SBL will depend on continued progress around collateral flexibility, documentation, settlement infrastructure, regulatory certainty, and active industry coordination.
How is the team managing expanding collateral acceptability parameters for different regions?
Imran Sheri: The collateral ecosystem is constantly evolving. Collateral acceptability cannot stay constant while the general market moves forward. Both have to work hand in hand. In Canada and Europe, non-cash collateral is overwhelmingly used for transactions, and with the cost of raising cash and balance sheet constraints, expanding non-cash collateral comes into greater focus. Lenders have to be in constant contact with brokers to understand how collateral can be expanded and potentially add new asset classes.
RBC uses a collaborative, risk-first framework to expand collateral acceptability. The process begins with RBC Investor Services conducting rigorous feasibility analysis on proposed asset classes to identify limitations, restrictions, and margin requirements while brokers provide market insights on collateral opportunities. Beneficial owners then conduct their own due diligence before new asset classes are added to service-level agreements and collateral schedules. Asset safety remains paramount, since beneficial owners grant RBC the privilege to lend their assets.
An example is Canadian pension plans, where RBC Investor Services coordinated with brokers, beneficial owners, and pension plans before adding Pension Paper as a standalone collateral entity, creating a new market outlet for their paper. This collaborative approach reflects how the Canadian collateral landscape is being transformed. With CCMS, general collateral baskets and secured general collateral (SGC), the Canadian collateral landscape is going through a structural change that will enhance and standardise collateral in the future.
There is an increased industry focus on capital-efficient lending structures. Where are you seeing increased uptake of various solutions like Pledge GMSLA and CCP to manage real-world assets?
Dexter Gall: While industry conversations increasingly centre on capital-efficient lending structures, market adoption remains measured. Our competitive positioning and organisational strength have insulated us from pressure to adopt these solutions in a wholesale way.
Take Pledge Global Master Securities Lending Agreement (GMSLA) structures as an example. Despite their theoretical appeal, uptake remains limited on both sides of the Atlantic. A meaningful shift could materialise if European undertakings for collective investment in transferable securities (UCITS) regulators and North American banking authorities provide stronger supervisory backing — but the timing and scale of such a shift remain uncertain.
Conversely, central counterparty (CCP) solutions have not yet gained traction with our trading counterparty base. This reflects current market realities: as infrastructure providers embed CCPs into standard workflows and securities financing transactions (SFT) regulatory frameworks become more CCP-friendly, we anticipate gradual migration. But this evolution will likely proceed incrementally rather than all at once.
Market solutions exist, but adoption hinges on regulatory clarity and operational integration — not just product innovation. Our focus remains on ensuring that whatever structures we adopt, they translate into tangible benefits for beneficial owners.
Which regions are showing the strongest lending demand right now, and how are you allocating inventory accordingly? How are regulatory changes impacting your strategy in different regions?
Chikhlia: Hong Kong, Taiwan, South Korea, and Japan continue to be standout markets, driving strong activity across the region. Asian equity lending revenues have remained robust through 2026, supported by demand across technology, semiconductor, and AI-related securities.
Against this backdrop, we remain focused on allocating inventory where borrower demand, utilisation, and lending spread provide the strongest risk-adjusted returns. Taiwan remains an important market, with foreign investors consistently accounting for more than 90 per cent of securities lending transaction values while Japan continues to provide depth and scale.
South Korea has also become increasingly relevant following the resumption of short selling in March 2025. The revised framework introduced enhanced requirements around institutional controls, naked short selling detection, and stock loan repayment periods. As a result, strong borrower demand needs to be considered alongside the operational and regulatory requirements associated with supporting that activity.
More broadly, APAC remains relatively fragmented, with significant differences in regulation, market infrastructure, and operating models. Our approach is therefore not simply to follow headline demand, but to optimise inventory based on market liquidity, regulatory certainty, collateral requirements, operational complexity, and our underlying clients’ risk appetite.
What were the top operational challenges you faced with T+1 adoption in North America, and which lessons are you now applying to APAC and Europe as they move toward shorter settlement cycles?
Kolodziejczyk: When navigating the move to T+1 in North America, our primary operational challenge within securities lending centred on two issues: the compression of the recall-to-settlement lifecycle and the behaviour change from clients and counterparties who require better infrastructure to act more quickly. Shorter settlement windows constrained the timeframe between cash market trade execution and loan recall deadlines, requiring alignment across agent lenders, clients, and counterparties to avoid underlying trade fails. Cross-border friction was further compounded by time zone mismatches and delayed trade allocations.
As Europe and APAC move toward accelerated settlement cycles, we are applying several critical operational lessons learned. Europe and the UK are targeting October 2027 for their aligned move to T+1, with detailed implementation, testing, and regulatory work already underway, giving us a deadline to prepare against. Recall processing must be near-fully automated end-to-end to meet tight T+0 notification cutoffs and remove batch-processing delays. To bridge geographic time gaps effectively, we are leveraging our global coverage model and multi-region operational footprint through follow-the-sun models, allowing regional teams to manage late-day trading activity, recall processing, and settlement seamlessly across time zones. The follow-the-sun model turns a time zone disadvantage into a structural strength.
In Asia, the transition will be market-by-market rather than region-wide as each jurisdiction has its own regulatory philosophy and FX realities. Our experience navigating T+1 in North America gives us a practical template, but the lesson we carry forward is that the template must adapt to each market’s imperatives.
A successful lending business requires synergy across teams. How do you foster collaboration across Toronto, London, and Singapore?
Barrand: Fostering collaboration across Toronto, London, and Singapore requires bridging massive geographic and cultural gaps. When the London desk opens, Singapore is winding down its day, and Toronto is asleep. To prevent these desks from operating as isolated silos, or worse, competing against one another, we focus on three core pillars: technological integration, financial alignment, and cultural connectivity.
With minimal time zone overlap, the handover of the global trading book must be flawless. Through synchronising the book handoff, we ensure the closing desk briefs the opening desk on any critical items, including pending locates, push lists, distressed fails, and borrower recalls that require round-the-clock attention. This includes utilising shared communication channels to ensure all team members have transparency to the same information.
A potential pitfall in a global securities lending programme is a flawed revenue attribution model. If each region is judged purely on its regional P&L, desks could potentially hoard special securities rather than transferring them to the region where they can capture the highest lending fee. Having access to a global inventory pool and a P&L structure centred around global business performance rather than regional desk revenue, ensures there is a collective and unified incentive to work as a team.
We create a virtual rotation of leadership and strategy meetings to ensure no single region feels isolated or disconnected from the global strategy. In recent years, we have sent traders to other regions, either on short-term assignments or as long-term permanent moves. This builds familiarity with local market nuances and exposes them to different regulatory and cultural environments.
What is your biggest technology opportunity today — is it integration, scalability, data, or something else?
Robert Instone: The area where we see the most opportunity is integration. Our business relies on a combination of internal and external platforms — such as triparty agents, data vendors, and post-trade reconciliation tools, among others — and it is vital to have seamless connectivity to fully utilise the benefits these platforms provide. We are continuously investing in tightening that connectivity, because every manual step we can automate translates directly into faster execution for our clients.
This pressure has been amplified by the move to T+1 settlement. With the reduced margin of error, there is a need to reduce operational friction. When a beneficial owner sells a security that is currently on loan, the lending desk must be notified (to the extent it cannot be reallocated) as early as possible to initiate a recall and avoid a settlement fail. Under T+1, the tolerance for late or missed notifications has effectively been eliminated. Without seamless and automated integration between our custody platforms and lending systems, these notifications can arrive too late to act upon and result in failed settlements, buy-in exposure, and potential reputational risk with counterparties and clients.
Whether it is internal or external, the ability to integrate seamlessly is more important than ever. Being able to bolt on tried-and-tested solutions to reduce manual workflows is a great advantage.
Looking ahead over the next 12 to 24 months, what is the single biggest ambition for the team?
Kolodziejczyk: Over the next 12 to 24 months, we are focused on achieving complete end-to-end automation of our securities lending lifecycle as we migrate to a new core securities lending platform. This modernisation initiative will replace our legacy systems and represents the next critical step in our platform evolution. By leveraging our technology capabilities alongside strategic vendor partnerships, we will eliminate operational bottlenecks and create a streamlined, integrated trading environment.
Barrand: Ultimately, this enables us to capture higher-margin opportunities, improve performance for our beneficial owners, and future-proof our operational infrastructure for emerging intraday and T+0 market trends. This positions us to expand into the new markets and client segments that our modernised infrastructure and follow-the-sun coverage now make more accessible.
Next interview →
Citi
Setting the standard

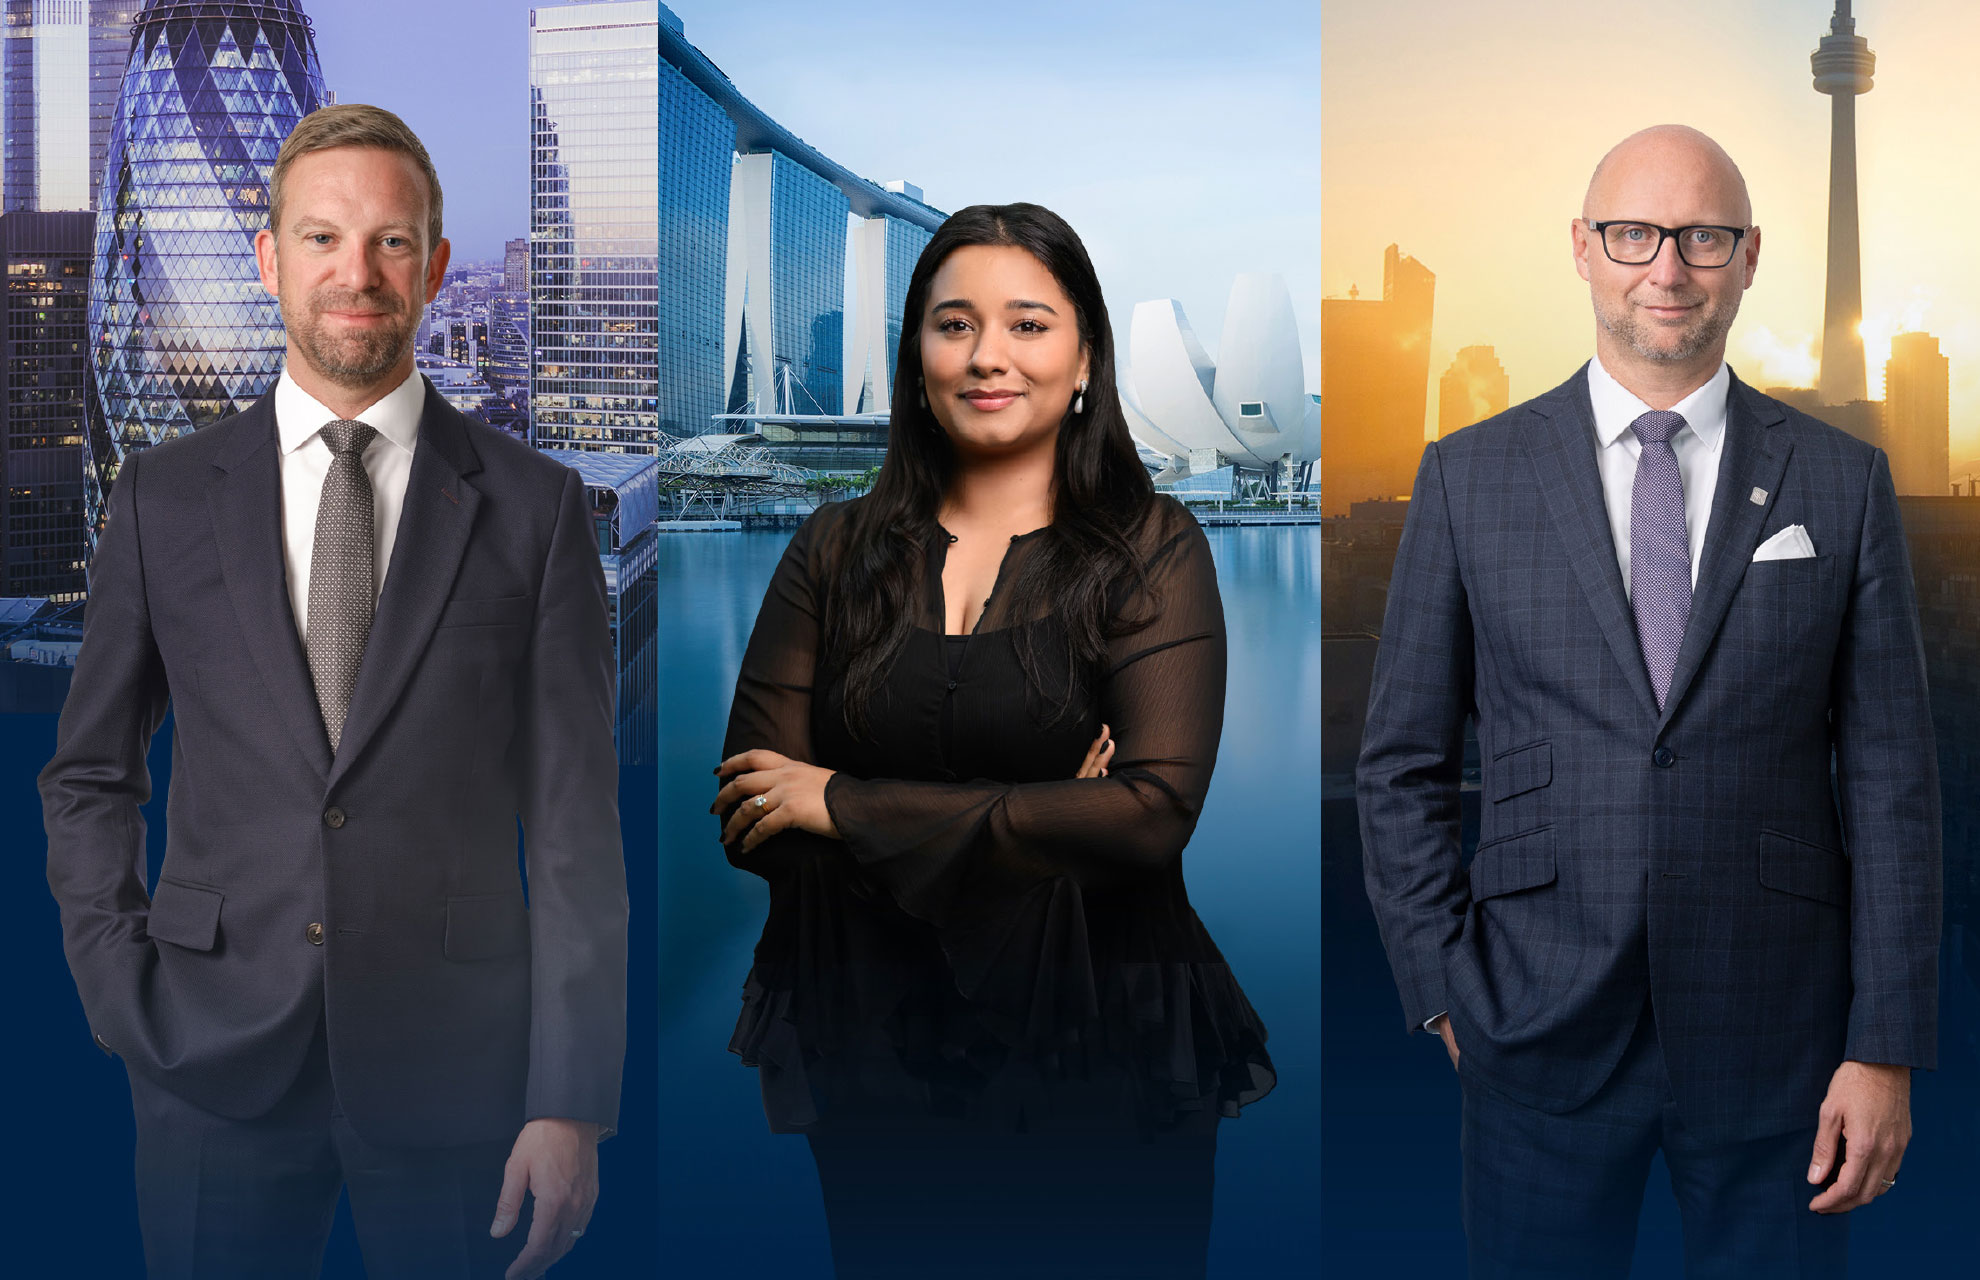 Image: RBC Investor Services