
SFS: T+1 readiness gaps persist as firms confront tighter recall and return timelines
25 September 2026 UK
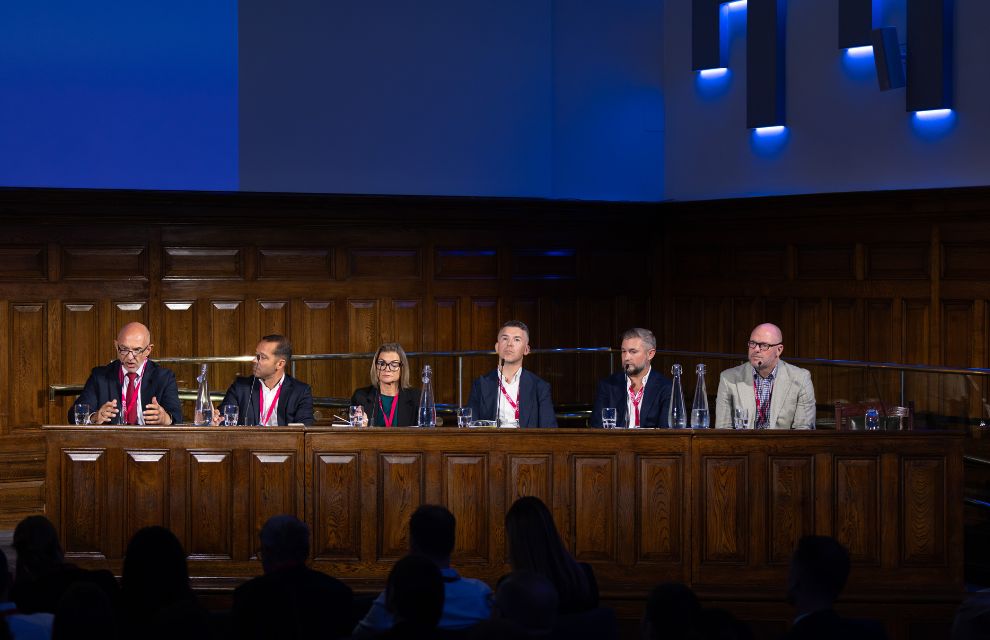 Image: SFT
Many firms remain unfamiliar with key requirements of T+1 despite years of discussion, said Roy Zimmerhansl, head of Capital Markets at WTS Hansuke, at the recent Securities Finance Symposium in London.
Moderating the ‘T+1: Thirteen Months Out and Still Asking the Hard Questions’ panel, Zimmerhansl explained: “We still hear people say they didn’t know about certain impacts.” He added that even regulators have admitted in the past they cannot reach their entire regulated base, leaving many buy side firms reliant on service providers for information.
Zimmerhansl highlighted the compressed timeline ahead of the 11 October 2027 go‑live. With 274 working days remaining, he said securities finance faces heightened pressure because its workflows sit inside cash market cut‑off windows. “We have to comply with all of the changes — but in even less time.”
Turning to readiness, Tony Holland, director of market practice at ISLA, shared findings from the EU T+1 Industry Committee latest readiness survey, which suggested that 83 per cent of firms are actively preparing, though notable gaps remain. 41 per cent of firms involved in fund share dealings have not yet developed their implementation plan, and more than half of all firms have not received guidance from their IT or service providers, creating a potential third-party dependency and implementation risk.
Holland reminded participants that UK and EU recommendations have been available for over 16 months. In the UK, they are underpinned by “the code of conduct” supported by the Bank of England, the Financial Conduct Authority (FCA), and HM Treasury. In the EU, the mantra is “adhere or explain”. He noted that while 2025 was focused on assessment and planning, “2026 is about development, build execution, and delivery”.
The panel then examined sale notifications, recalls, and returns. Rickie Smith, head of EMEA agency securities finance product at J.P. Morgan, said compressed timelines make early client notifications critical. “Getting the recall out is one thing, but the return is just as critical,” he said. He warned that behavioural patterns and custody‑chain constraints continue to create friction.
Smith said tighter T+1 windows increase the risk of settlement failures, buy‑ins, penalty exposure, and entitlement breaks. He added that firms need documented operating agreements and service level agreements covering cut‑off times, late‑recall handling, partial returns, and exception ownership. “The quicker clients can get instructions to the agent lender, the higher the likelihood the recall can support underlying cash‑market settlement.”
Turning to trading and liquidity, Olivier Zemb, head of equity finance and collateral management at Caceis, said firms should expect timing mismatches. “The first thing I see is the persistence of mismatches and the increased repercussions of those in the context of T+1. The misalignment of DVP and FOP cutoffs is not new but we may see a higher number of recalls settling between the 2 windows due to shorter settlement cycles.
As a consequence, CSDR penalties could be higher. The question then is who is liable for these penalties. Some rewording of the GMSLA may be needed to clarify this.”
He also stated that he does not anticipate higher buffers or over-recalls but rather a reallocation of traded volume from less efficient participants to more reliable counterparts. “The likelihood of execution will probably become a more important parameter to assess best execution than it is today.”
Zemb said partial settlement and partial returns may improve efficiency, but only if lending chains and cash market settlement teams are aligned. He highlighted the need for clearer specifications and more standardised processes across the chain.
The panel then looked at operational accuracy. Matthew Neville, managing director and head of agency lending trading, EMEA, at State Street, explained that agent lenders must ensure inventory positions published from their lending systems are “as accurate as possible” so borrowers have certainty when they execute orders on T+0. Although most lending activity is conducted for T+1 today, we expect more same-day demand from borrowers since they will likely not see their net demand requirements from their clients until the following morning.
He highlighted that increased activity at the close will require all parties in the value-chain to expedite trade instructions to their providers to ensure borrows and recalls can be executed timely. He emphasised the use of vendor tools to automate post-trade workflows, including pre-matching, regular refreshing of RQVs (Required Collateral Values), and automated loan-release post-collateralisation at the triparty agents, to minimise the manual touchpoints and expedite settlement given we will have less time to solve mismatches.
According to Neville, lenders are already co-ordinating with borrowers on a bilateral basis to ensure trading parameters, including prepays and electronic execution cut offs are suitable per borrower entity, as demand and collateral distribution capabilities may differ depending on location.
Gabi Mantle, global head of client success and solutions engineering at Equilend, highlighted lessons from the US and Canadian transitions. She reported a 183 per cent rise in recall volume and a 27 per cent increase in recall relationships since January 2025 – already seven months after the US/CAD move to T+1 which had already seen significant uptake. “You don’t have time for manual processing.”
Mantle described efforts to improve efficiency higher up the chain, including a complete revamp of SSI repositories. Logins and data extraction have risen by 1,000 per cent, with SSIs “finally getting a seat at the table”. She added that pre‑matching is too late under T+1, and firms need short selling regulation SSIs and place of settlement data embedded at the point of execution.
A panellist noted that future market models, including same‑day repo funding, tokenised collateral, and delivery‑versus‑delivery concepts, will shape the longer‑term move toward T+0.
In closing, panellists urged firms to coordinate across the full lifecycle and strengthen communication with clients, service providers, and counterparties. “You can’t just prepare for yourself — you need to bring your client base with you,” one panellist said. They encouraged firms to review processes, align trading and settlement teams, and verify counterparties’ plans ahead of the accelerated settlement cycle.
Moderating the ‘T+1: Thirteen Months Out and Still Asking the Hard Questions’ panel, Zimmerhansl explained: “We still hear people say they didn’t know about certain impacts.” He added that even regulators have admitted in the past they cannot reach their entire regulated base, leaving many buy side firms reliant on service providers for information.
Zimmerhansl highlighted the compressed timeline ahead of the 11 October 2027 go‑live. With 274 working days remaining, he said securities finance faces heightened pressure because its workflows sit inside cash market cut‑off windows. “We have to comply with all of the changes — but in even less time.”
Turning to readiness, Tony Holland, director of market practice at ISLA, shared findings from the EU T+1 Industry Committee latest readiness survey, which suggested that 83 per cent of firms are actively preparing, though notable gaps remain. 41 per cent of firms involved in fund share dealings have not yet developed their implementation plan, and more than half of all firms have not received guidance from their IT or service providers, creating a potential third-party dependency and implementation risk.
Holland reminded participants that UK and EU recommendations have been available for over 16 months. In the UK, they are underpinned by “the code of conduct” supported by the Bank of England, the Financial Conduct Authority (FCA), and HM Treasury. In the EU, the mantra is “adhere or explain”. He noted that while 2025 was focused on assessment and planning, “2026 is about development, build execution, and delivery”.
The panel then examined sale notifications, recalls, and returns. Rickie Smith, head of EMEA agency securities finance product at J.P. Morgan, said compressed timelines make early client notifications critical. “Getting the recall out is one thing, but the return is just as critical,” he said. He warned that behavioural patterns and custody‑chain constraints continue to create friction.
Smith said tighter T+1 windows increase the risk of settlement failures, buy‑ins, penalty exposure, and entitlement breaks. He added that firms need documented operating agreements and service level agreements covering cut‑off times, late‑recall handling, partial returns, and exception ownership. “The quicker clients can get instructions to the agent lender, the higher the likelihood the recall can support underlying cash‑market settlement.”
Turning to trading and liquidity, Olivier Zemb, head of equity finance and collateral management at Caceis, said firms should expect timing mismatches. “The first thing I see is the persistence of mismatches and the increased repercussions of those in the context of T+1. The misalignment of DVP and FOP cutoffs is not new but we may see a higher number of recalls settling between the 2 windows due to shorter settlement cycles.
As a consequence, CSDR penalties could be higher. The question then is who is liable for these penalties. Some rewording of the GMSLA may be needed to clarify this.”
He also stated that he does not anticipate higher buffers or over-recalls but rather a reallocation of traded volume from less efficient participants to more reliable counterparts. “The likelihood of execution will probably become a more important parameter to assess best execution than it is today.”
Zemb said partial settlement and partial returns may improve efficiency, but only if lending chains and cash market settlement teams are aligned. He highlighted the need for clearer specifications and more standardised processes across the chain.
The panel then looked at operational accuracy. Matthew Neville, managing director and head of agency lending trading, EMEA, at State Street, explained that agent lenders must ensure inventory positions published from their lending systems are “as accurate as possible” so borrowers have certainty when they execute orders on T+0. Although most lending activity is conducted for T+1 today, we expect more same-day demand from borrowers since they will likely not see their net demand requirements from their clients until the following morning.
He highlighted that increased activity at the close will require all parties in the value-chain to expedite trade instructions to their providers to ensure borrows and recalls can be executed timely. He emphasised the use of vendor tools to automate post-trade workflows, including pre-matching, regular refreshing of RQVs (Required Collateral Values), and automated loan-release post-collateralisation at the triparty agents, to minimise the manual touchpoints and expedite settlement given we will have less time to solve mismatches.
According to Neville, lenders are already co-ordinating with borrowers on a bilateral basis to ensure trading parameters, including prepays and electronic execution cut offs are suitable per borrower entity, as demand and collateral distribution capabilities may differ depending on location.
Gabi Mantle, global head of client success and solutions engineering at Equilend, highlighted lessons from the US and Canadian transitions. She reported a 183 per cent rise in recall volume and a 27 per cent increase in recall relationships since January 2025 – already seven months after the US/CAD move to T+1 which had already seen significant uptake. “You don’t have time for manual processing.”
Mantle described efforts to improve efficiency higher up the chain, including a complete revamp of SSI repositories. Logins and data extraction have risen by 1,000 per cent, with SSIs “finally getting a seat at the table”. She added that pre‑matching is too late under T+1, and firms need short selling regulation SSIs and place of settlement data embedded at the point of execution.
A panellist noted that future market models, including same‑day repo funding, tokenised collateral, and delivery‑versus‑delivery concepts, will shape the longer‑term move toward T+0.
In closing, panellists urged firms to coordinate across the full lifecycle and strengthen communication with clients, service providers, and counterparties. “You can’t just prepare for yourself — you need to bring your client base with you,” one panellist said. They encouraged firms to review processes, align trading and settlement teams, and verify counterparties’ plans ahead of the accelerated settlement cycle.
NO FEE, NO RISK
100% ON RETURNS If you invest in only one securities finance news source this year, make sure it is your free subscription to Securities Finance Times
100% ON RETURNS If you invest in only one securities finance news source this year, make sure it is your free subscription to Securities Finance Times