OCC
No longer a niche: OCC stock loan programme looks ahead after more than a decade of growth
13 October 2026
Daily loan value in OCC’s stock loan programmes has grown nearly seven-fold since 2013. Now the clearing house is looking to triparty, the buy side, and tokenisation for what comes next, explores OCC’s Harsh Devpura, director of securities finance, and Nathan Ice, managing director, treasury, collateral services and securities financing
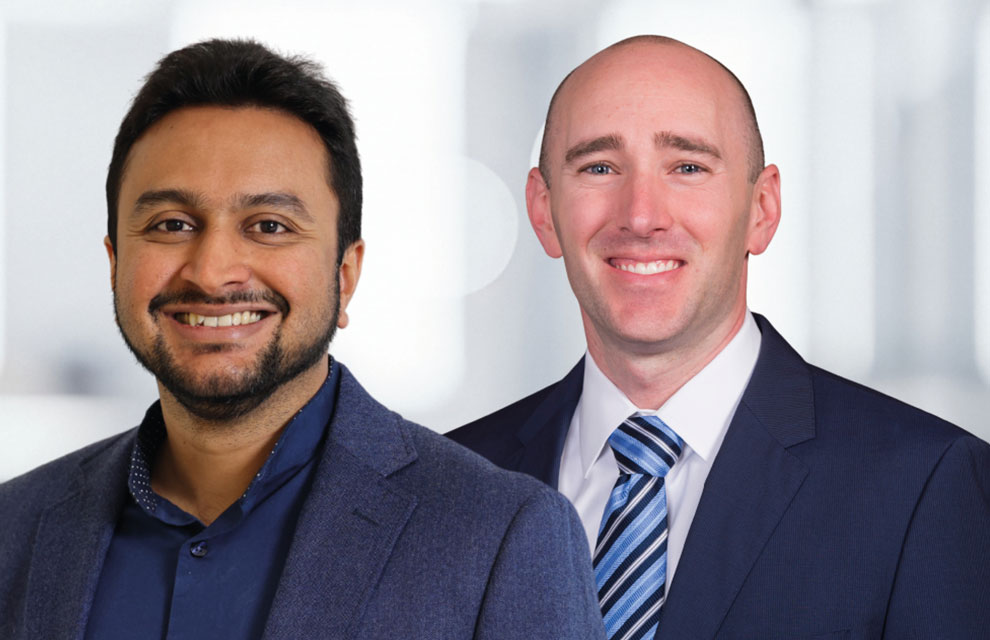 Image: OCC
The Options Clearing Corporation’s (OCC’s) role in the options market is well known. Less visible, but growing rapidly, is its role in securities lending. Since 1993, OCC has offered clearing members a centrally-cleared path to lend and borrow securities. Under the stock loan/hedge programme, loans are negotiated bilaterally between clearing members and then novated to OCC for clearing and guarantee.
Under the market loan programme, launched in 2009, lenders and borrowers are matched anonymously, OCC instructs settlements, and post-settlement loans are novated and guaranteed the same way. Both programmes let clearing members allocate positions daily for maximum margin relief, and both carry OCC’s guarantee against counterparty default. The market loan programme adds a further guarantee on dividend-equivalent and rebate payments.
That guarantee is not incidental. OCC’s status as a qualifying central counterparty (CCP) delivers, on average, 90-95 per cent in risk-weighted asset (RWA) savings compared to uncleared lending activity, while removing bilateral counterparty credit risk from the equation entirely.
Just as importantly, clearing consolidates what would otherwise be a sprawling web of bilateral relationships into a single connection to OCC, simplifying operations for existing members and lowering the barrier for new ones to scale. Capital efficiency, risk reduction, and operational simplicity are why the stock loan programme has become a key lever clearing members use to manage their securities financing books.
Securities financing sits inside OCC’s broader role as a systemically important financial market utility (SIFMU): a risk-based margin methodology that responds dynamically to market conditions, a robust clearing fund built to cover the default of its two largest members, and geographically diverse operations designed to keep clearing and settlement running through periods of stress. It is the same foundation the options market has relied on for more than 50 years, extended to securities lending over the last three decades.
More than a decade of compounding growth
Growth in OCC’s stock loan clearing has not been gradual; it has compounded. Daily loan value across the hedge and market loan programmes combined has grown from roughly US$36 billion in 2013 to around US$245 billion as of 30 September 2026, while average daily shares on loan have grown from roughly 817 million to more than 6.8 billion over the same period. That works out to a compound annual growth rate of 16.9 per cent and 18.5 per cent, respectively, sustained across 13 years. The most recent four years alone have compounded at a faster pace, which is the real signal: this is not a one-off spike, but a structural shift.
Much of that growth traces back to capital efficiency. Post-crisis regulatory reform meant a bilateral stock loan to a broker-dealer could carry a risk weight of up to 100 per cent, against as little as two per cent for the same loan cleared through a qualifying CCP, a gap that has pulled banks and broker-dealers deeper into clearing ever since.
The number of firms participating has grown alongside the volume: OCC’s stock loan clearing membership has expanded from 53 firms in 2013 to 79 firms today.
In 2023, the SEC approved a rule change expanding OCC’s clearing membership eligibility beyond broker-dealers, futures commission merchants, and non-US securities firms to include qualifying banks. The response has been strong with State Street joining OCC in 2025 as a participant acting on a principal basis.
Three decades ago, the programme was a small tool to help options traders and market makers run riskless reverse conversions or hedge against their options portfolio. Today it clears tens of thousands of loan positions daily. The direction of travel is consistent: more activity, more participants, and more of the securities financing market moving onto cleared, guaranteed rails.
Bringing collateral together: Triparty
OCC views securities finance through the lens of helping members mobilise assets efficiently and directing scarce collateral to where it creates the greatest value. To that end, OCC is investing in triparty collateral management.
Today, collateral for OCC’s Clearing Fund and Margin requirements moves across a distributed network of settlement banks, depositories, and custodians, each operating on its own schedule. That structure works, but it adds complexity: delivery delays can create settlement risk, and members lack a single portfolio view across all their collateral obligations, making it harder to allocate the lowest-cost eligible assets first.
A triparty model addresses this by centralising collateral operations through a specialised agent, while OCC’s direct relationship with its members stays exactly the same. It is already how a large share of the world’s collateral moves — triparty agents now hold a record US$14.49 trillion in assets globally.
For members, the benefits are concrete: better collateral allocation reduces funding costs, automated eligibility screening and margin calls reduce operational risk, and a broader network of counterparties supports more competitive funding rates. For OCC, a centralised platform replaces today’s fragmented processing with a single, scalable infrastructure, built with the API access and data transparency to expand into new asset types as the market evolves.
Investing in the future of OCC
OCC wants to bring the same capital efficiency to the buy side as it does to its clearing members. Agent lenders and beneficial owners who lend bilaterally today, outside the cleared ecosystem, stand to gain much of what OCC’s existing members already have: lower regulatory capital costs from facing a qualifying CCP; access to a wider pool of borrowers than any single bilateral relationship offers; reduced counterparty credit risk and lower indemnification costs, since exposure to many counterparties is replaced with exposure to one highly-rated CCP; relief from single-counterparty credit limits that constrain bilateral volume; and netting of settlement obligations, which reduces settlement costs.
OCC is evaluating more than one way to bring agent lenders into clearing, including new access models and stock loan clearing product expansion, so that lenders of different sizes can find a fit.
One question OCC hears from members, in different forms, is about tokenisation. The answer is straightforward: OCC is looking at it carefully and deliberately to determine how it may help mobilise collateral more efficiently, and how it can support liquidity at scale where it is needed most.
Tokenisation and distributed ledger technology do not change what securities finance is about. What they offer is a faster, transparent, more programmable way to do it.
OCC is engaged with industry groups and evaluating pilots to validate collateral mobility benefits across asset classes through tokenisation.
As markets edge toward round-the-clock trading and settlement, the infrastructure being built today is also the starting point for whatever comes next. Central to that is Ovation, the cloud-based platform onto which OCC is moving its core clearing and risk functions, a move for which OCC was the first SIFMU to receive an SEC Notice of No Objection. OCC plans to harmonise the Stock Loan/Hedge and Market Loan programmes into a single structure with an expanded guarantee following the launch of Ovation.
OCC is building the levers now, so that when the market is ready to pull them, they will already be in place.
← Previous interview
Saphyre
Ready-to-lend becomes real